
How to File a Roof Insurance Claim in Wentzville, Missouri
To file a roof insurance claim in Wentzville, MO, document visible damage safely, arrange professional help to prevent further water entry, review your policy and deductible, and contact your insurer promptly. Keep dated photographs, receipts, and a communication log, then prepare for the insurer's adjuster inspection. A roofing contractor can document construction damage and provide a written repair estimate; the insurer decides coverage under your policy.
You do not need to climb onto the roof or know whether every mark is storm damage before asking for help. Start with what you can observe safely, and distinguish what you know from what still needs inspection.
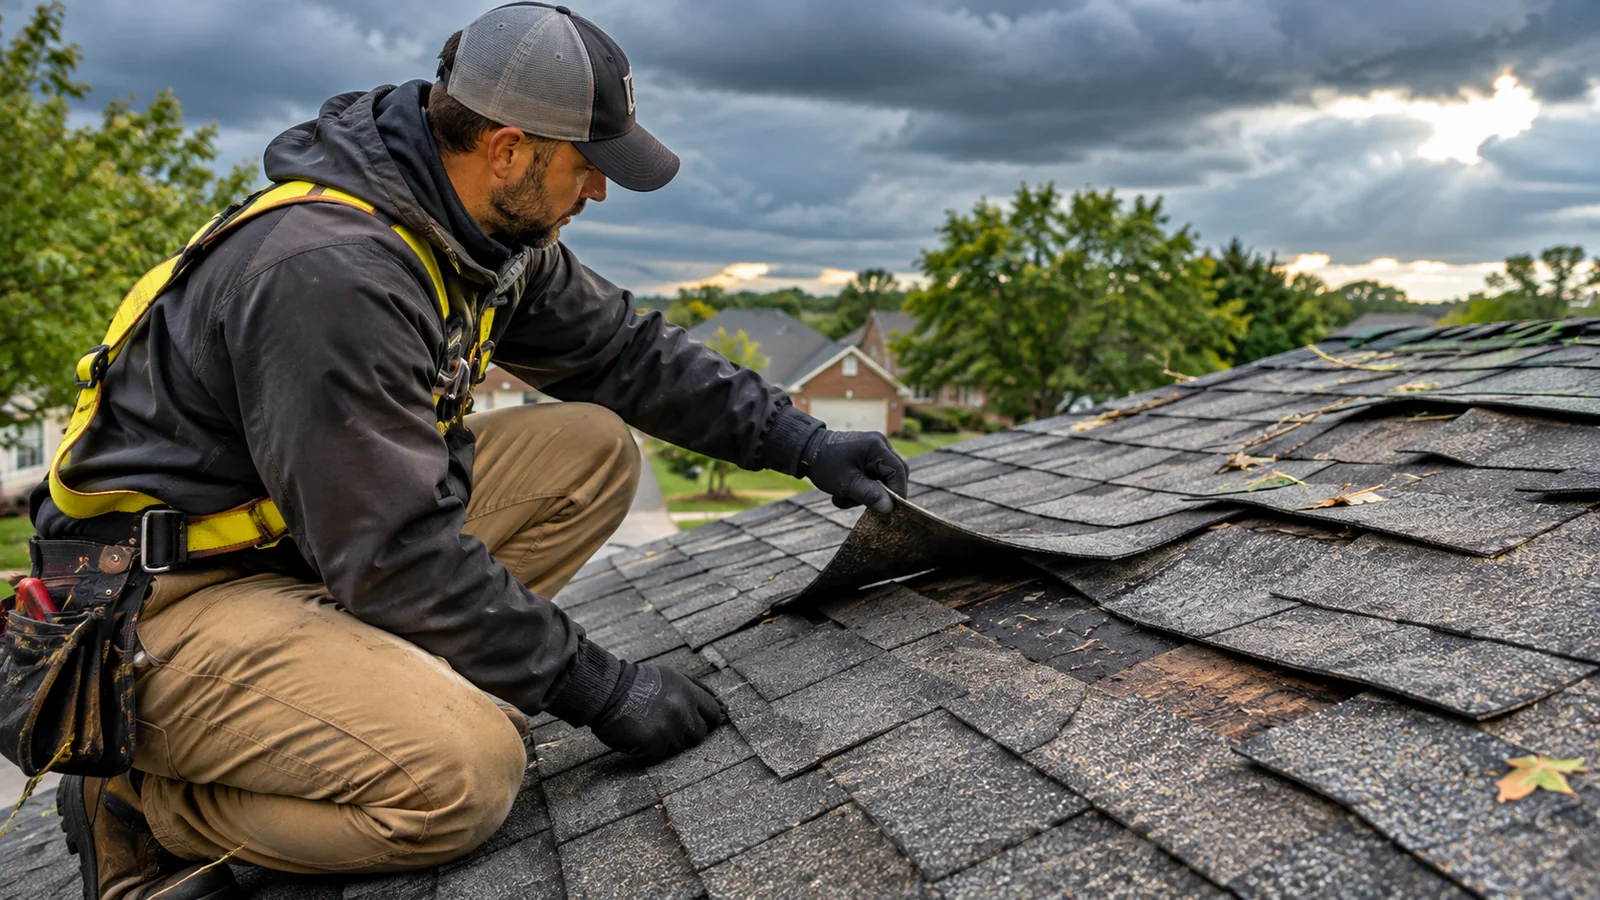
1. Identify possible damage without climbing the roof
Wait until severe weather has passed. From a safe ground-level position, look for missing shingles, displaced roof materials, debris, or damaged gutters. Indoors, note new ceiling stains or dripping water. These observations justify a closer assessment; they do not establish the cause, extent, or insurance eligibility of a loss.
The Insurance Institute for Business & Home Safety explains that hail can damage roof coverings and allow water to affect ceilings, walls, and belongings. A roof can need professional evaluation even when the ground-level view is inconclusive.
Do not use a ladder, walk on the roof, or install a tarp yourself. Stay away from fallen power lines, unstable limbs, sagging ceilings, and water near electrical equipment. Leave dangerous areas and seek appropriate emergency or qualified professional help. A storm-damage roof assessment should focus on observable construction conditions, not promises that insurance will pay.
2. Build a dated record tied to your property
Create one folder for photos, notes, receipts, and correspondence. Take wide views showing where an issue is located, then closer images only where safely accessible. Preserve original files and record when each photo was taken. Include interior damage and affected belongings, not just the roof.
- Record the suspected weather date separately from the date you first noticed damage.
- Describe locations clearly, such as the ceiling above an upstairs bedroom or the gutter along the driveway.
- Save earlier roof photos, maintenance records, and repair invoices if available.
- Keep a log of calls, names, dates, and requested next steps.
For Wentzville homeowners, the National Weather Service St. Louis office provides regional storm reports and event summaries. Save relevant weather information as context, but do not treat a nearby hail report as proof that your address sustained damage. Avoid guessing a loss date when a stain appears after several rainy days; explain the timeline honestly.
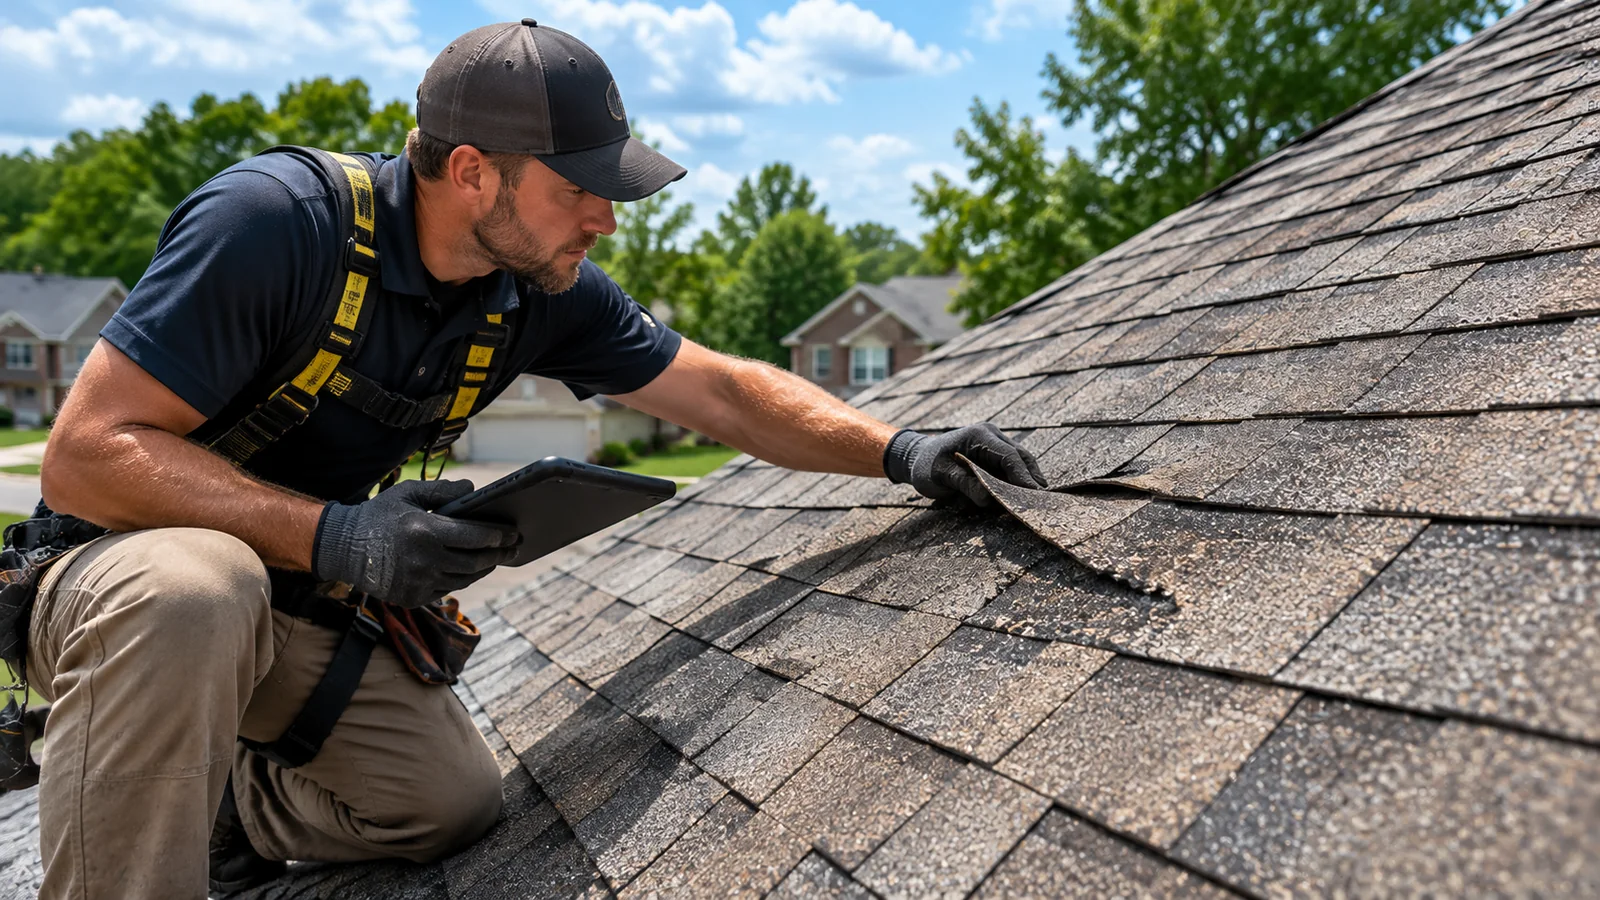
3. Mitigate water entry while preserving evidence
If water is entering, do not wait for the entire claim process to finish before seeking safe mitigation. Move belongings only if the area is safe. Arrange professional temporary protection or roof repair assessment rather than attempting a dangerous tarp installation.
Missouri's severe-weather insurance guidance recommends necessary temporary repairs to prevent further damage and keeping receipts. It also cautions against permanent repairs before the insurance company inspects the damage. Tell your insurer about urgent conditions and ask how to document necessary protective work.
Ask the contractor to photograph conditions before and after temporary work and describe what was protected. Keep invoices and material receipts; reimbursement depends on coverage and claim review. If immediate work is necessary for safety, explain why and preserve whatever evidence can be collected safely. For more on recognizing water-entry problems, see our roof leak repair guide.
4. Read the policy, endorsements, and deductible
Gather the declarations page, full policy, and endorsements, which modify the policy. Missouri's roof insurance coverage guide emphasizes that those documents determine coverage. Storm damage and ordinary wear are not interchangeable, and a new stain does not by itself establish a covered cause.
Actual cash value coverage accounts for depreciation. Replacement cost coverage uses a different settlement basis, but it does not eliminate policy conditions or guarantee complete roof replacement. Ask your insurer to explain how your specific roof coverage works.
- Which deductible applies, and is there a separate wind or hail deductible?
- Are there roof-specific exclusions, limits, or age-related provisions?
- What notice, documentation, or repair deadlines apply?
- What conditions apply to any recoverable depreciation?
A site-specific written estimate can help you understand the potential scope alongside the deductible. Avoid relying on neighborhood claim stories: another Wentzville homeowner's policy, roof condition, and documented loss may differ from yours.
5. Notify the insurer and prepare for the inspection
Contact your agent or the insurer's claims department promptly, using contact details from your policy or the company's official website. Report the facts you know: when damage was discovered, the suspected cause if known, and whether water is entering. Ask whether the conversation opens a claim and request the claim number if one is created.
Confirm how to submit photographs, mitigation receipts, and contractor reports. Ask about inspection scheduling and anything the adjuster needs to see before permanent work. Do not delay required notice while waiting for a contractor estimate.
For the appointment, organize your evidence and identify affected areas from a safe location. Verify the adjuster's identification. Ask whether the insurer permits your contractor to attend to explain roof conditions and the proposed repair scope. Request an explanation of the inspection findings and next steps, including how to submit additional information if a construction item appears overlooked.
6. Keep construction advice separate from claim representation
A roofer's role is technical: inspect roof components, document damage, take measurements, and explain feasible repairs. A written estimate should identify proposed materials and work, distinguishing observed damage from conditions that cannot be confirmed without further access. If roof replacement is recommended, ask why repair is insufficient.
The insurer's adjuster evaluates the claim for the insurance company. A Missouri-licensed public adjuster is a separate professional who may represent a policyholder in claim negotiations. Hiring one is not required to file a claim. Roofing documentation is not public-adjuster representation or legal advice, and a contractor cannot guarantee approval.
If the insurer's assessment and contractor's findings differ, ask for written reasons and submit specific photos or scope details for review. For questions about claim handling, Missouri DCI offers consumer assistance and a complaint process. Do not sign a repair agreement merely because someone says approval is certain.
Homeowner Questions
Frequently asked questions
Can I file a roof claim without visible missing shingles?
Yes, but the absence of missing shingles does not establish or rule out damage. Report observable symptoms honestly and arrange a professional assessment. Neither a ceiling stain nor a nearby storm report proves that your policy covers the loss.
Should I call a roofer or my insurance company first?
If water is entering, prioritize safe professional mitigation and notify your insurer promptly. Otherwise, an inspection can help clarify the condition, but do not let scheduling delay policy-required notice. Ask the insurer what evidence it needs before permanent repairs.
Can Gray Summit Roofing handle negotiations as my public adjuster?
Gray Summit Roofing's role is construction assessment and estimating, not public-adjuster representation. A contractor can explain documented damage and repair requirements. Claim negotiation on your behalf is a distinct role for an appropriately licensed professional; the insurer determines coverage.
Does a wind or hail claim automatically cover a whole new roof?
No. The documented damage, repair needs, policy language, exclusions, and deductible matter. Ask for the insurer's written explanation of covered scope. A contractor's replacement recommendation is construction advice, not a guarantee of full replacement coverage.
What if the adjuster misses damage or I disagree with the estimate?
Identify the specific disputed area or work item and submit dated photos and a written contractor explanation. Ask how the insurer reviews additional evidence or requests for another inspection. Keep responses in your claim file and contact Missouri DCI with claim-handling concerns.
Helpful sources
Request a documented roof inspection and written estimate
For your Wentzville home, contact Gray Summit Roofing LLC about an inspection and written estimate, or call 314-886-1489. Based at 3132 W Osage St, Pacific, MO 63069, Gray Summit Roofing serves Greater St Louis. Ask for clear documentation of roof conditions and proposed work you can share with your insurer; coverage remains the insurer's decision under your policy.